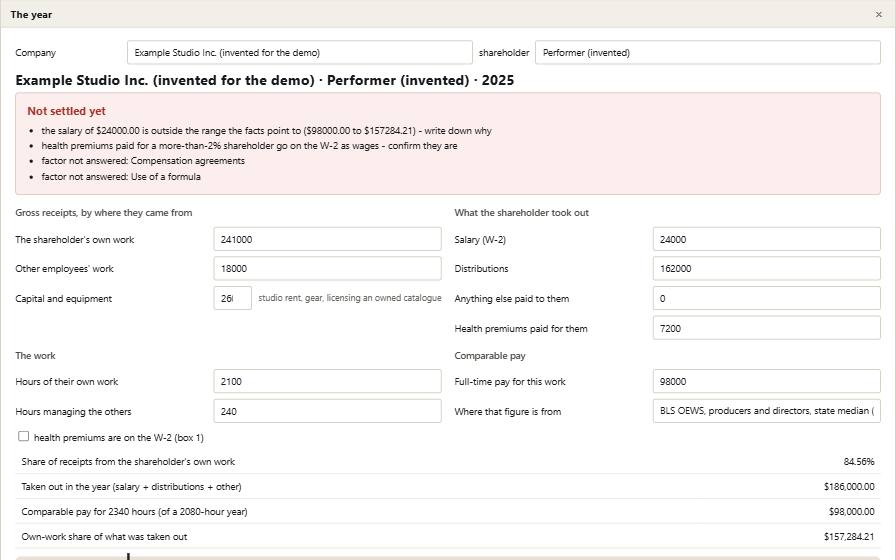
Stipend shows where the facts point for an S corporation’s reasonable salary: receipts split by source — the shareholder’s own work, other employees, capital and equipment — the hours worked, comparable pay and where it came from, and the IRS’s nine factors answered. The owner decides; Stipend makes the decision a dated record.
Opens in this browser with an invented creator’s company already in it. No account, no email address, nothing installed.
Open the free demo →
The problem
The IRS says an S corporation must pay reasonable compensation to a shareholder-employee for their services before non-wage distributions may be made, and can reclassify distributions as wages. The key is where the receipts come from. For a performer whose income is almost all their own work, the facts usually point to a lot more salary than they would like.
training, duties, time, distribution history, pay to others, bonuses, comparable pay, agreements, formula.
distributions the IRS treats as wages, with the payroll tax that comes with them.
Not a reminder. Record the decision refuses, with the reason named, while receipts, comparable pay or hours are missing, distributions were paid with no salary, the salary is outside the range with no written reason, health premiums are not on the W-2, or any of the nine factors is unanswered. There is no override.
How it works
Receipts by source, what you took out, hours of your own work and of managing others, and comparable full-time pay with its source.
The IRS’s list, each in a line or two.
The range the facts point to, your salary on it, the payroll tax it carries, and W-2 box 1. Kept year by year.
What it will never do
Stipend never picks the salary. The owner decides, with their adviser, and Stipend records why.
Pricing
The one line an examiner always questions.
One S corporation, one shareholder.
Two S corporations or two shareholders.
Yearly licence. Your bank statement says Stipend Software. Refunded in full on request within 30 days. Your licence key is emailed to you within two working days of payment.
Checkout is our own bitcoin server, not a card processor — nobody we had to apply to and nobody who can close the account. The button takes you straight to it. Give your email address there — that is where your key is sent.
Questions
Receipts from your own work point to wages. Receipts from other employees, or from capital and equipment, can properly be distributions.
No. Reasonable compensation is never more than the shareholder actually received.
For a more-than-2% shareholder, premiums go in W-2 box 1. Stipend checks it.
No. It is the record of how you decided.
The demo on this page is the whole program, running on invented records. Paying gets you a licence key — one line of text, emailed to the address you give at checkout within two working days. Paste it into the program and from then on it keeps your own records. Until then, nothing you type into it is kept.
The key is checked inside the page, on your own machine. It never calls us, so there is still no account and nothing about your business goes anywhere. If you ever stop paying, your records stay exactly where they are, read-only, and Export still hands you every one of them.
The invented creator’s company pays a $24,000 salary against $186,000 taken out, with health premiums off the W-2 and two factors unanswered. Stipend shows where the facts point.